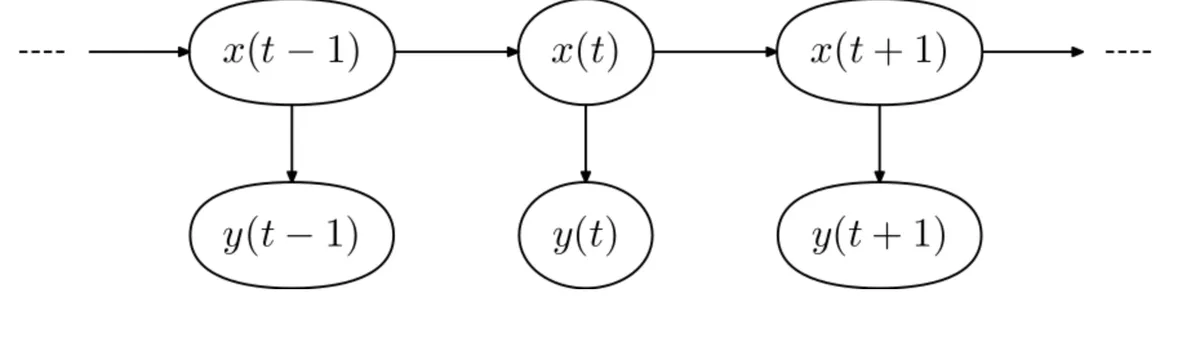
Hidden Markov Model
A hidden Markov model is a Markov Chain with a single discrete state variable with domain and a single, discrete evidence variable.
The Transition Model
is a single matrix.
The Sensor Model
is an -vector.
The idea is that we can now formulate Markov Inference as matrix calculations (which can be sped up by optimized algorithms).
To make this work we create a diagonal sensor matrix from the Sensor Model vector.
Filtering
Smoothing
Zustandsraum
Emissionen
Sensor Model
Anfangsverteilung
Beispiel Veranschaulichung